A brand is a promise with a service charge attached. Pay for scarce promises, kept by operators bound for decades.
 ByAbhii Dabas
2026 in four numbers
| Figure | What it measures |
|---|---|
| 910 | Branded schemes globally at end-2025, up 19% in a year |
| 1,747 | Total schemes once the contracted pipeline lands by 2032 |
| ~33% | Average global price premium over non-branded |
| +59% | Growth in developments forecast in the five years to 2029 |
Sources: Savills 2025/26, Knight Frank survey.
The seven, in order
1. Dubai
The global showcase, where the product meets its perfect buyer: tax-driven, mobile, service-hungry UHNW demand landing on Golden Visa rails. Scarcity discipline matters most here precisely because supply keeps coming.
2. Miami
The heart of the market’s largest region: North America holds the biggest share of global schemes, and Miami is its branded capital, from waterfront towers to automotive-brand debuts.
3. London
Heritage stock meets five-star operators, with completed Marylebone-to-Mayfair schemes anchoring Europe. The prime central London correction (around 7.0% in the year to Q1 2026, per Knight Frank) prices the entry.
4. Costa del Sol
Europe’s fastest-growing branded cluster, drawing safe-haven demand from US, Middle Eastern, and Northern European buyers into Marbella and its coastline.
5. Bangkok
The face of Asia-Pacific’s 55% five-year growth, pairing branded towers with the city’s new UK-school campuses, which puts two 2026 demand stories in one market.
6. Vietnam
The supply frontier: a named driver of the APAC surge alongside Thailand and India, with early-cycle pricing and the diligence burden that comes with it.
7. Mexico
The resort-premium play: resort locations carry the highest branded premiums, around 39% per Savills, and the Riviera Maya is where that number lives.
On INTRIC now — Residences on INTRIC are open to enquiry straight from this page.
NEXT Address
Apartment · 11 Tbel Abuseridze Str, Batumi, 6010, Georgia
USD 50.9K – USD 191.2K
Five Palm Jumeirah
APARTMENT · Five Palm Jumeirah, West Beach, Palm Jumeirah, Dubai, United Arab Emirates
AED 2.15M – AED 2.38M
Apartment Building in Higashi-ku, Fukuoka
COMMERCIAL · Kasumigaoka 2-chome, Higashi-ku, Fukuoka, Japan
From JPY 185.00M
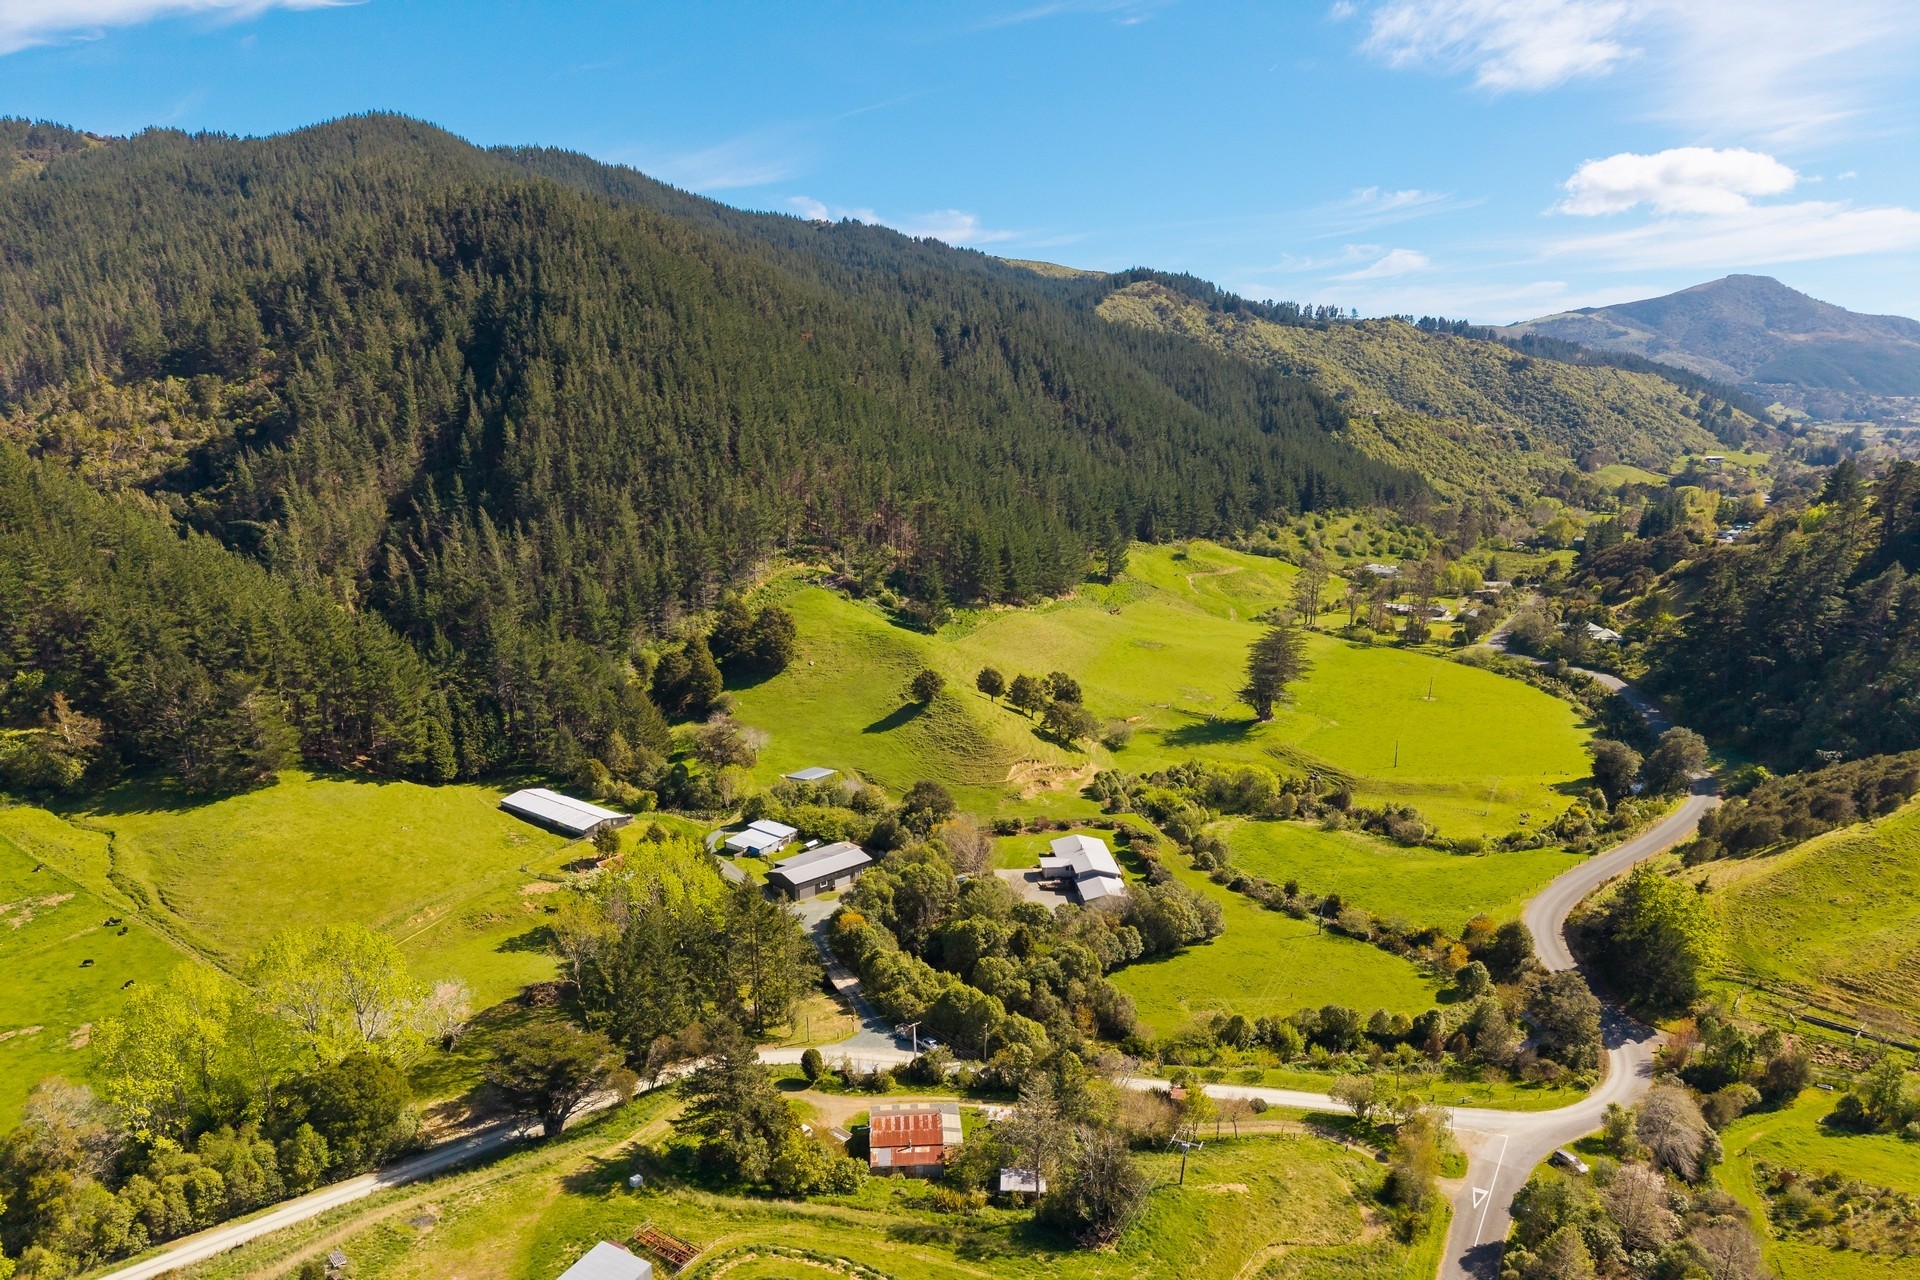
312 Lud Valley Road
HOUSE · 312 Lud Valley Road, Hira, Nelson 7071, New Zealand
The 2026 picture side by side
| Market | Why it leads | The 2026 note |
|---|---|---|
| Dubai | The global showcase; deep UHNW demand and tax pull | Pairs the product with Golden Visa and zero income tax demand drivers |
| Miami / US | The US dominates the global project count | North America holds the largest regional share of schemes |
| London | Prime heritage stock meets five-star operators | Marylebone-to-Mayfair completions anchor the European market |
| Costa del Sol | Europe’s fastest-growing branded cluster | Safe-haven demand from US, Middle East, and Northern European buyers |
| Bangkok | Asia-Pacific’s 55% five-year growth story | Thailand is a named driver of the APAC surge |
| Vietnam | The emerging supply frontier | A named driver of Asia-Pacific growth alongside Thailand and India |
| Mexico | Resort-led premiums | Resort locations carry the highest premiums, around 39% per Savills |
Sources: Savills Branded Residences 2025/26, Knight Frank Global Branded Residence Survey, sector coverage 2025-2026.
The brand as a proxy for trust
Why do cross-border buyers overweight branded residences? Because the brand substitutes for the local knowledge they do not have. A buyer landing in a new market cannot easily verify build quality, management standards, or rental performance; a global operator’s name is a bond posted against all three. That is why the category over-indexes in exactly the markets cross-border capital favours: Dubai, Miami, London, and the resort coasts.
On INTRIC now — Still open on INTRIC — every one of these answers enquiries directly.
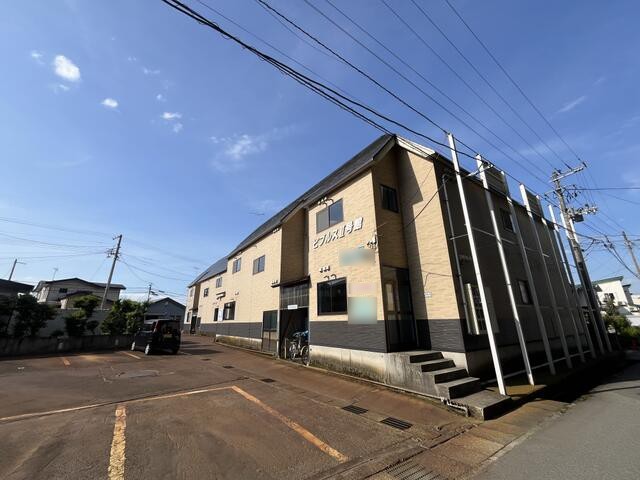
Apartment Building in Gobyo, Yonezawa
COMMERCIAL · Gobyo 1-chome, Yonezawa, Yamagata, Japan
From JPY 50.00M
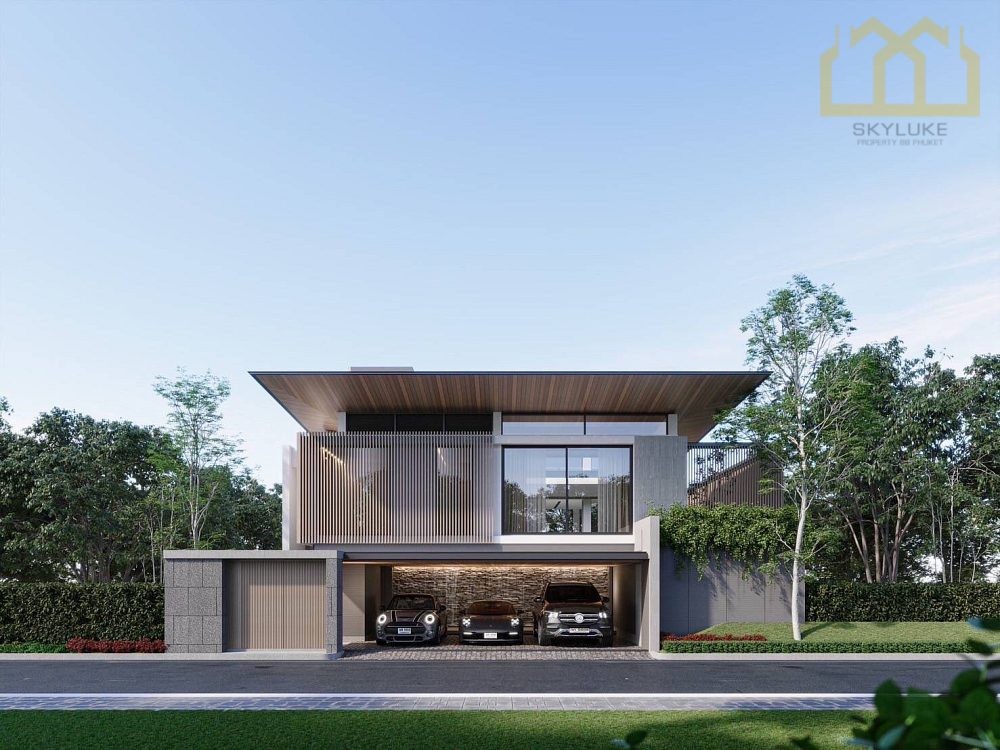
4-Bedroom Villa in Rawai, Mueang Phuket
HOUSE · Rawai, Mueang Phuket, Phuket, Thailand
From THB 34.80M
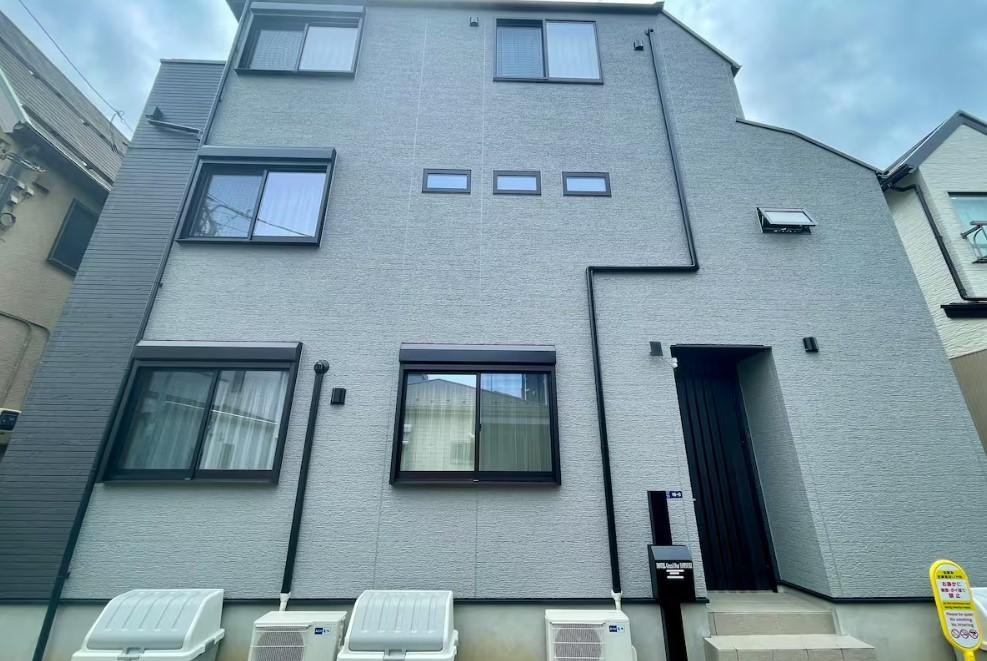
Ryokan in Katsushika-ku, Tokyo
COMMERCIAL · Yotsugi 1-chome, Katsushika-ku, Tokyo, Japan
From JPY 120.00M
2-Bedroom Apartment in Lagos
APARTMENT · Lagos, Faro, Portugal
From EUR 640K
Before you pay the premium
- Check brand scarcity in that specific city: premiums compress where the same tier of brand is oversupplied.
- Read the brand agreement: length, renewal terms, and what happens to services if the operator exits.
- Model service charges over a ten-year hold and test resale evidence, not launch pricing.
A brand is a promise with a service charge attached. Pay for scarce promises, kept by operators bound for decades.
Read the full intelligence report
“The name on the door: branded residences in 2026” goes deeper on the full supply and pipeline data, the premium decomposition, and the four-point brand diligence screen. Access it through the free Explorer tier at intricglobal.com/en/subscribe.
Frequently asked questions
How many branded residences exist in 2026?
Around 910 schemes at end-2025, nearly triple the 2015 count, with contracted projects taking the total toward 1,747 by 2032 across more than 90 countries, per Savills.
What premium do branded residences command?
Around 33% globally on average per Savills, about 39% in resorts, with Knight Frank framing 20% to 35% over comparable non-branded stock.
Which region is growing fastest for branded residences?
Asia-Pacific, up 55% in five years driven by Vietnam, Thailand, and India, per Savills.
Do branded residences hold their premium on resale?
Knight Frank data associates branded stock with stronger resale and rental performance, but the premium erodes in oversupplied markets, so test resale evidence for the specific scheme and city.
This article is information only and is not tax, legal, immigration, or investment advice. Rules change frequently and vary by circumstance; take qualified professional advice. Property values can fall as well as rise and capital is at risk. Figures are rounded and attributed to Savills and Knight Frank.
Abhii Dabas is the Founder and CEO of INTRIC Global, the cross-border property intelligence platform for serious investors. He advises high-net-worth buyers on international real estate strategy and has evaluated residential markets across more than 40 countries.