City guides
City guides (458)
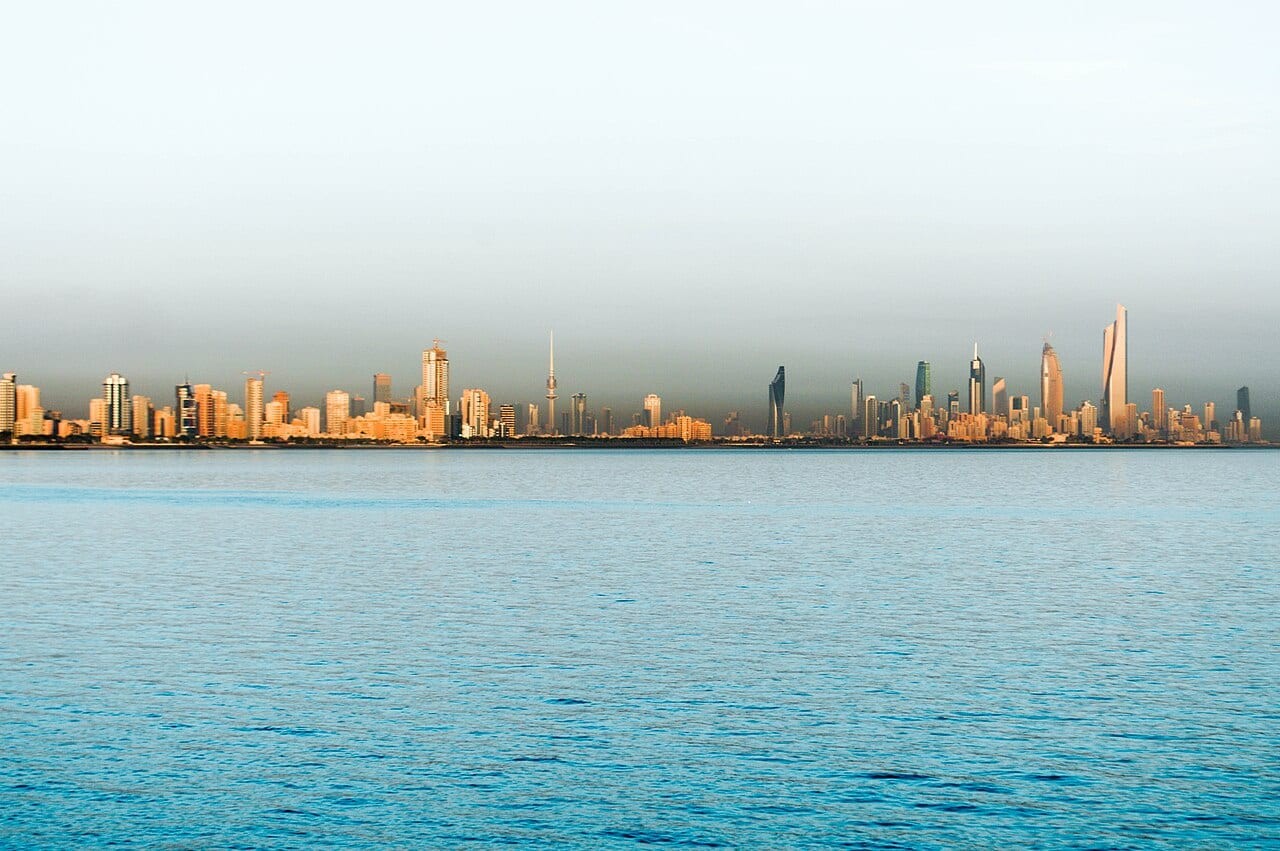

Kuwait City Guide
Kuwait
Kuwait City is the capital and financial heart of one of the Gulf's wealthiest petrostates, concentrating the country's government, banking sector, and the Kuwait Stock Exchange within the Capital (Al Asimah) Governorate. The market is structurally different from Dubai or Doha: foreign freehold ownership is heavily restricted, so the investable opportunity centres on the Istithmari (investment) apartment segment, where cap rates ran a robust 6.45% to 7.06% in Q1 2025 - among the most attractive income profiles in the Gulf. Activity rebounded strongly heading into 2025, with real estate sales surging almost 28% in Q4 2024 to KD1,082 million, the highest in more than two years, and commercial land prices in Kuwait City up 28.5% year-on-year in Q3 2024. The prime rental districts cluster along the coast and central corridor - Bneid Al Gar (where investment land values rose 7.7%), Sharq with its waterfront towers and Souk Sharq, the bustling Salmiya retail belt in neighbouring Hawalli, and Mahboula to the south - all drawing steady tenant demand from the large expatriate workforce. The 2025 outlook is constructive, supported by an improving non-oil economy, the Kuwait Vision 2035 diversification agenda, and prospective interest-rate cuts, though investors must navigate ownership rules and a market driven more by stable income than rapid capital appreciation.

Jurmala City Guide
Latvia
Stretching some 32 kilometres of pine-fringed white sand along the Gulf of Riga, just 25 kilometres west of the Latvian capital, Jūrmala is the Baltic region's premier coastal resort town and the heart of Latvia's second-home and premium-property market. Famous for its Art Nouveau wooden summer villas, spa hotels and the elegant promenades of Majori, the concert halls of Dzintari, and the bohemian leafy streets of Bulduri, the town draws affluent buyers from across the Baltics, the Nordics and beyond. Latvia's premium real estate segment posted a record first half of 2025, with transaction volume above EUR 250 million, up roughly 28% year-on-year and the strongest in five years, and Jūrmala captured a disproportionate share of that activity, accounting for over half of registered premium land deals. Apartment prices in the Kauguri district averaged around EUR 812 per square metre in 2025 (up 4.1% year-on-year), while detached resort villas commonly trade between EUR 250,000 and EUR 350,000, with exclusive seafront plots averaging close to EUR 480,000. As a Eurozone member with no currency risk, Jūrmala offers international buyers a tranquil, high-quality lifestyle alternative to Riga with a resilient luxury segment.
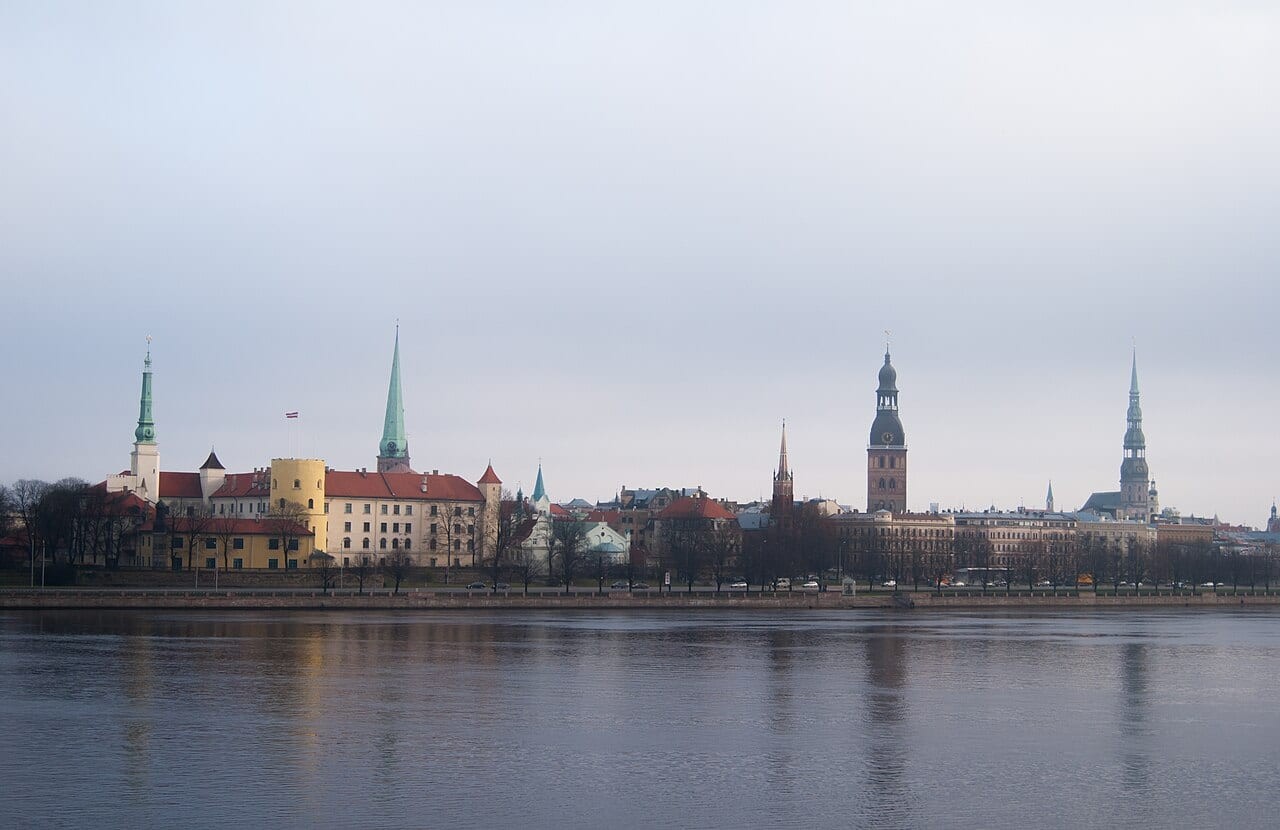
Riga City Guide
Latvia
Riga is the capital of Latvia and the largest city in the Baltic states (~592,000 residents). As a full EU and eurozone member (Latvia adopted the euro in 2014), it offers foreign investors EU-grade legal protections, a euro-denominated market and a fast digital land register. Riga is best known for possessing the largest concentration of Art Nouveau (Jugendstil) architecture in the world, roughly a third of central buildings are Art Nouveau, with Alberta iela and Elizabetes iela holding some of Northern Europe's most ornate façades. Together with the medieval Old Town (Vecrīga), this central core forms a UNESCO World Heritage Site, genuine architectural scarcity at price points far below comparable Western heritage capitals. For investors, Riga is a value-and-yield market rather than a capital-growth play. Central renovated and new-build apartments trade at roughly €2,000–4,300/m² (exclusive Old Town and Quiet Centre stock reaching €5,000–7,000/m²), while the dominant Soviet-era 'series' apartment stock in the suburban microdistricts averaged just €865/m² in September 2025. Gross rental yields are among the highest of any EU capital, Global Property Guide put the Riga average at ~8.6% in 2025, though this headline is inflated by small peripheral units; realistic central-district yields are 6.7–7.6%. Latvia's residence-by-investment route remains open (minimum €250,000 in completed property plus a one-time 5% state duty; Russian and Belarusian applicants are excluded), a live driver of central demand, 201 investment-permit approvals in 2025, up ~35%. The bull case is tempered by real headwinds: demographic decline, a NATO-frontline geopolitical risk premium, and the loss of the traditional Russian/Belarusian buyer pool since 2022.

Kaunas City Guide
Lithuania
Lithuania's second city and interwar former capital, Kaunas recorded the fastest property-price growth in the country in 2025, with average apartment prices rising 13.8% to about EUR 2,071 per square metre, the largest annual change of any Lithuanian city. The market is driven by a structural shortage of high-quality new housing in convenient locations, with completions falling for two consecutive years while demand from international-company employees, students, and public-sector workers keeps central districts tight. Typical older apartments range EUR 1,400-2,400 per square metre, leaving Kaunas materially cheaper than the capital Vilnius. Kaunas also delivers some of Lithuania's strongest yields, averaging around 5.8%, with studios and older stock reaching 6-7%; rents jumped roughly 13% in 2025, outpacing price growth and improving the income case. The Naujamiestis (New Town) modernist core, a UNESCO World Heritage site, along with Zaliakalnis, Centras, and Senamiestis (Old Town) form the prime zones. A NATO build-up that will base thousands of German troops near Vilnius and Kaunas through 2025-2026 adds incremental family-rental demand. With a population near 298,000 and Eurozone, EU, and NATO membership, Kaunas enters 2026 as Lithuania's standout value-and-yield market.
Vilnius City Guide
Lithuania
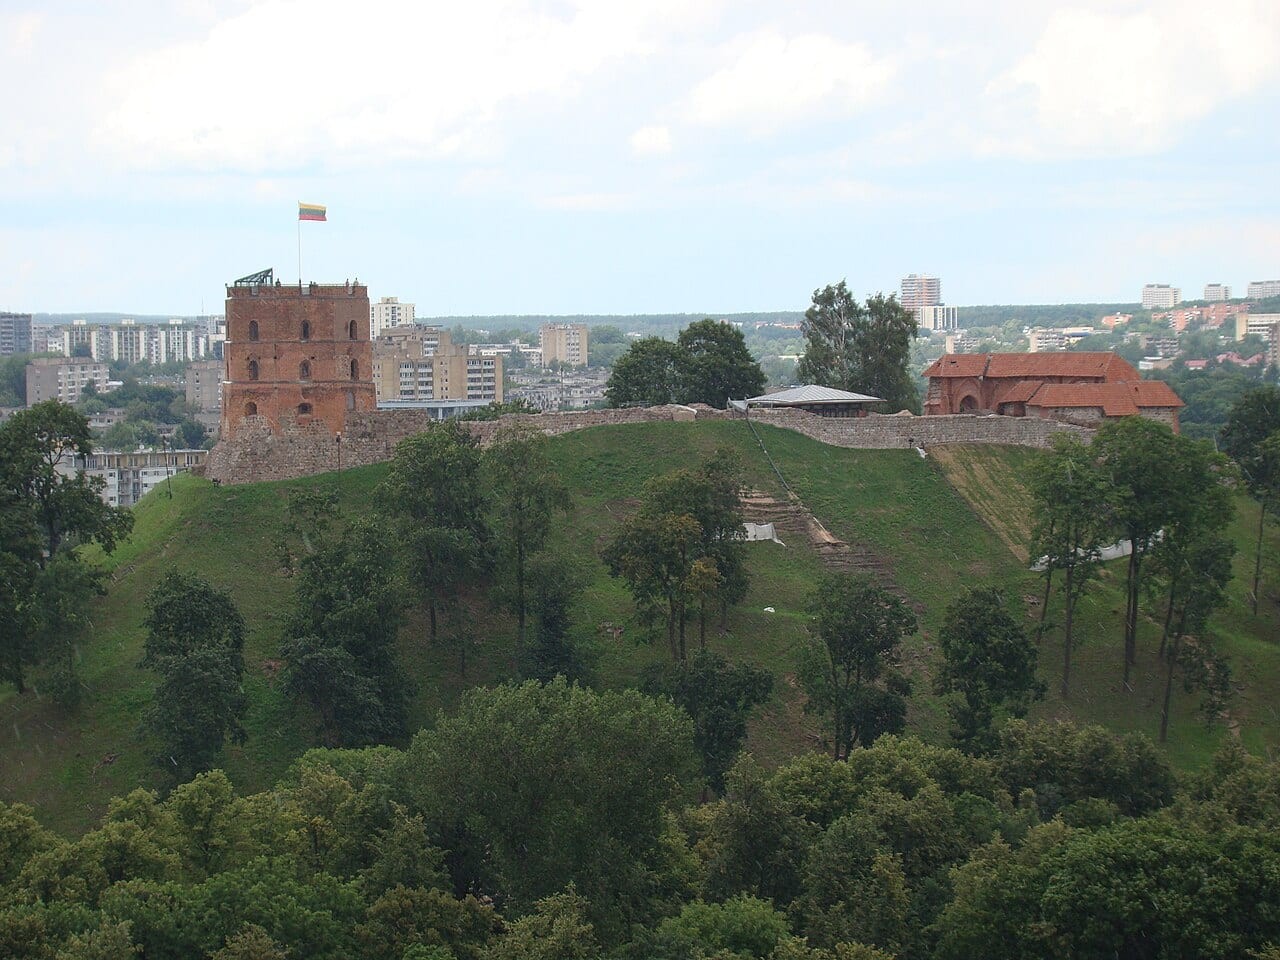
Vilnius is the capital and largest city of Lithuania, recently overtaking Riga as the biggest in the Baltic states. It is best known for its baroque UNESCO World Heritage Old Town (Senamiestis), one of the largest surviving medieval/baroque old towns in Europe, paired with an aggressive ring of modern development on the north bank of the Neris, where the Baltics' largest Central Business District (the Šnipiškės skyscraper district) has risen since 2000. Lithuania has used the euro since 1 January 2015, removing currency risk for euro-denominated investors. The economy underpinning the market is among the EU's most dynamic. Lithuania ranks first in the EU by number of licensed fintech companies, is a world leader in laser/photonics (its lasers are used by most of the world's top universities) and has a fast-growing life-sciences cluster. Vilnius is the hub of this activity, sustaining a deep pool of high-income local and expat tenants. On price, Lithuania has been one of the EU's fastest-appreciating markets over the past decade, house prices rose roughly +168% between 2015 and Q4 2025 (third only to Portugal and Bulgaria, per Eurostat); Vilnius apartments averaged ~€2,930/m² in December 2025, up ~10.7% over the trailing year (Ober-Haus). Gross rental yields citywide sit in the ~5–6% band, below the national average because prime-centre capital values are high relative to rents. Lithuania has NO property golden visa (residence requires genuine active business), and short-term-rental rules are in flux: a 2026 reform is expected to legalise STR in residential/multi-unit buildings (currently a legal grey zone), and the EU short-term-rental registration regime applies from 20 May 2026.

Flic-en-Flac City Guide
Mauritius
Flic-en-Flac is Mauritius's principal west-coast beach town, fronting one of the island's longest stretches of white sand and a calm, reef-protected lagoon. For foreign buyers it is one of the most accessible entry points into the island's regulated investment schemes: the Property Development Scheme (PDS) allows non-citizens to purchase at a minimum of USD 375,000, which also confers a renewable residence permit for the holder and dependents. Local agents place beachfront stock here roughly 15-20% below comparable Grand Baie prices in the north, broadening the buyer pool. The town's draw is lifestyle and tourist-rental income: diving, water sports, the nearby Casela nature park, and easy access to Port Louis via improved highway links. PDS pipeline projects of apartments, penthouses, and villas are scheduled through 2026, supported by the Cascavelle Shopping Village expansion. Note that the resident town population is small (around 2,000), so demand is overwhelmingly tourism- and second-home-driven rather than domestic. With Mauritius's 15% flat tax, no inheritance tax, and political stability, Flic-en-Flac suits lifestyle investors seeking sun, beach, and residency in a single purchase.
Grand Baie (Mauritius North Coast) City Guide
Mauritius
Mauritius is the Indian Ocean's premier property-investment destination, a politically stable, English/French-speaking island with a low-tax regime (no capital-gains or inheritance tax) and a property-linked residency programme that is unusually generous by global standards. Foreigners cannot buy residential land freely; they purchase through government-approved schemes administered by the Economic Development Board, primarily the Property Development Scheme (PDS, which replaced IRS/RES in 2015), the Smart City Scheme, and Ground+2 (G+2) apartments. The headline draw is direct: buying a qualifying property worth at least US$375,000 under PDS or Smart City grants the buyer and dependents a residence permit, valid for as long as the property is held. Grand Baie is the undisputed resort and lifestyle capital of the north coast, the 'Côte d'Azur of Mauritius'. It pairs a sheltered turquoise bay with the island's densest concentration of fine dining, nightlife, retail (La Croisette mall with 110+ stores; Grand Baie Coeur de Ville), marinas and watersports. This lifestyle infrastructure underpins the strongest property values on the island, anchoring a cluster of prime northern coastal villages (Pereybere, Pointe aux Canonniers, Mont Choisy, Cap Malheureux, Grand Gaube) that share its amenity base at distinct price points. Property in the prime segment is priced and transacted in EUR or USD even though the local currency is the Mauritian rupee (MUR), insulating overseas buyers from currency noise. The thesis combines lifestyle, residency, a benign tax environment and robust short-let demand from year-round tourism. NOTE, time-critical fiscal change: foreign-buyer registration duty doubles from 5% to 10% on deeds registered from 1 July 2026 (Finance Act 2025).

Chișinău City Guide
Moldova
Chișinău is the capital and largest city of Moldova and the undisputed centre of the country's economy, government, and property market, home to the great majority of national commercial activity within the Chișinău Municipality. As Moldova advances its EU-candidate path, the capital has seen sharp price appreciation: apartment values reached a record of about €1,720 (≈US$1,860) per square metre by end-March 2025, up 11.7% from end-2024, before largely plateauing through the rest of the year. Newer 'white-shell' apartments trade above €1,400/m² while older Soviet-era stock sits nearer €970/m². The standout feature for investors is yield, Moldova's gross rental yield averaged about 8.65% in Q3 2025, among the highest in Europe, driven by strong rental demand from internal migration to the capital, diaspora investment, and a structural housing shortage where demand is estimated to outstrip supply by 20–30%. Rents grew 25–30% in 2024. The risks are significant, however: transaction volumes fell about 37% year-on-year in the first three quarters of 2025 as effective demand softened, and Moldova's proximity to the war in Ukraine, its small economy, and political uncertainty all weigh on the outlook.
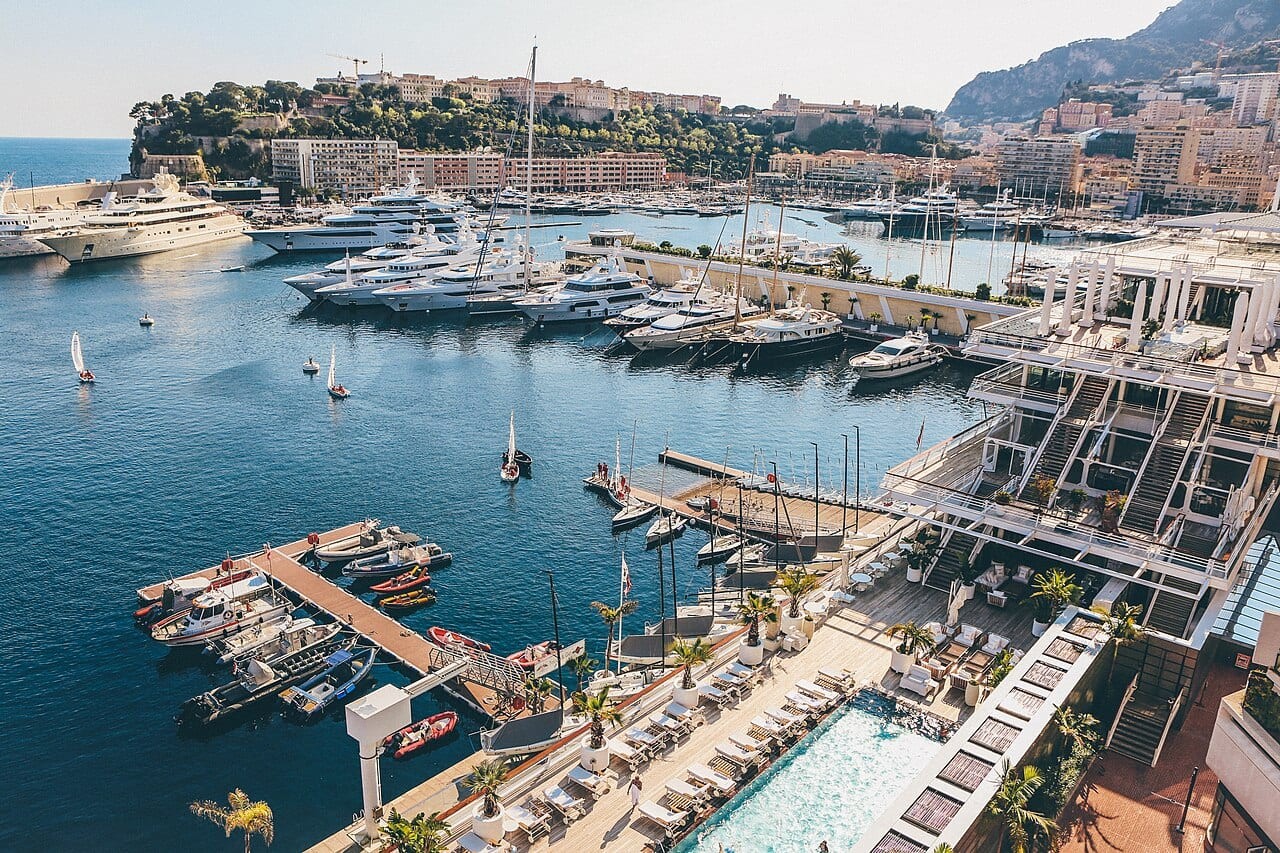

Monaco City Guide
Monaco
The Principality of Monaco is the world's most expensive residential market and a zero-personal-income-tax ultra-prime safe haven, where structural land scarcity (just ~2 km²) and demand from 140+ nationalities keep capital values among the highest on earth. Resale prices average around €52,000/m², reaching €100,000+/m² in trophy buildings and the new Mareterra eco-district. The state-affiliated Société des Bains de Mer anchors a luxury economy around the Casino de Monte-Carlo and its flagship hotels and beach clubs. For investors it is a capital-preservation and lifestyle play: yields are among the world's lowest (~1.5–3%), but scarcity has driven roughly 5% average annual price growth over three decades.
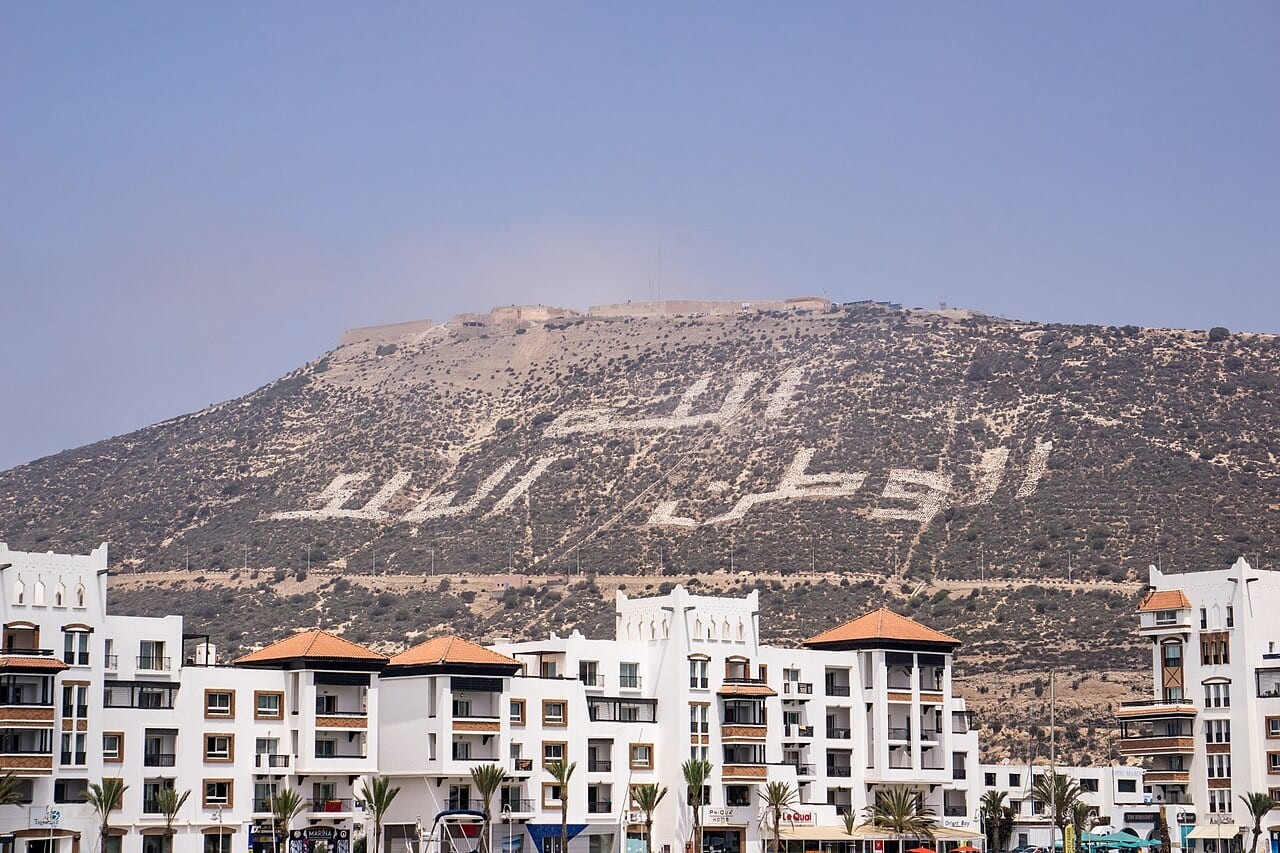

Agadir City Guide
Morocco
Agadir is Morocco's premier Atlantic beach-resort city and capital of the Souss-Massa region, rebuilt on a modern grid after the 1960 earthquake and marketed on 300-plus sunshine days, a long sandy bay and steady tourism. Foreigners may freely buy urban and residential property here, with agricultural land the only significant restriction. As of September 2025 city-centre apartments averaged about MAD 12,800/m2 and suburban stock about MAD 9,400/m2, and nominal prices were broadly flat to slightly negative over the year, a neutral-to-soft signal worth noting. Yields vary sharply by district: premium expatriate-targeted apartments in Founty and Sonaba run roughly 6-7% gross, while budget stock in Talborjt and outer areas can reach 8-10%, albeit with Talborjt now seen as approaching saturation. The blended city average is about 4.8%.
Casablanca
Morocco
Casablanca is Morocco's economic capital and largest city -- the country's commercial, banking, and industrial centre. Unlike tourism-driven Marrakech, Casablanca is a working business city anchored by the Casablanca Finance City (CFC) -- a regulated financial hub designed to be Africa's financial gateway, alongside Royal Air Maroc HQ, OCP (one of the world's largest phosphate producers), and major Moroccan banks. Residential prices in prime districts (Anfa, Maarif, CIL, Bourgogne, Gauthier) range from MAD 12,000-25,000 per square metre (USD 1,200-2,500), with gross yields of 5.0-7.0%. The market is dominated by long-term rental tenants -- corporate executives, finance professionals, and international workers at multinational regional offices. For international buyers, Casablanca offers African financial hub status, USD/EUR-stable currency, no foreign ownership restrictions, and a more institutional tenant base than Marrakech. The catch: it's a working city without Marrakech's tourist appeal, short-let opportunities are limited, and traffic and urban density are challenging.
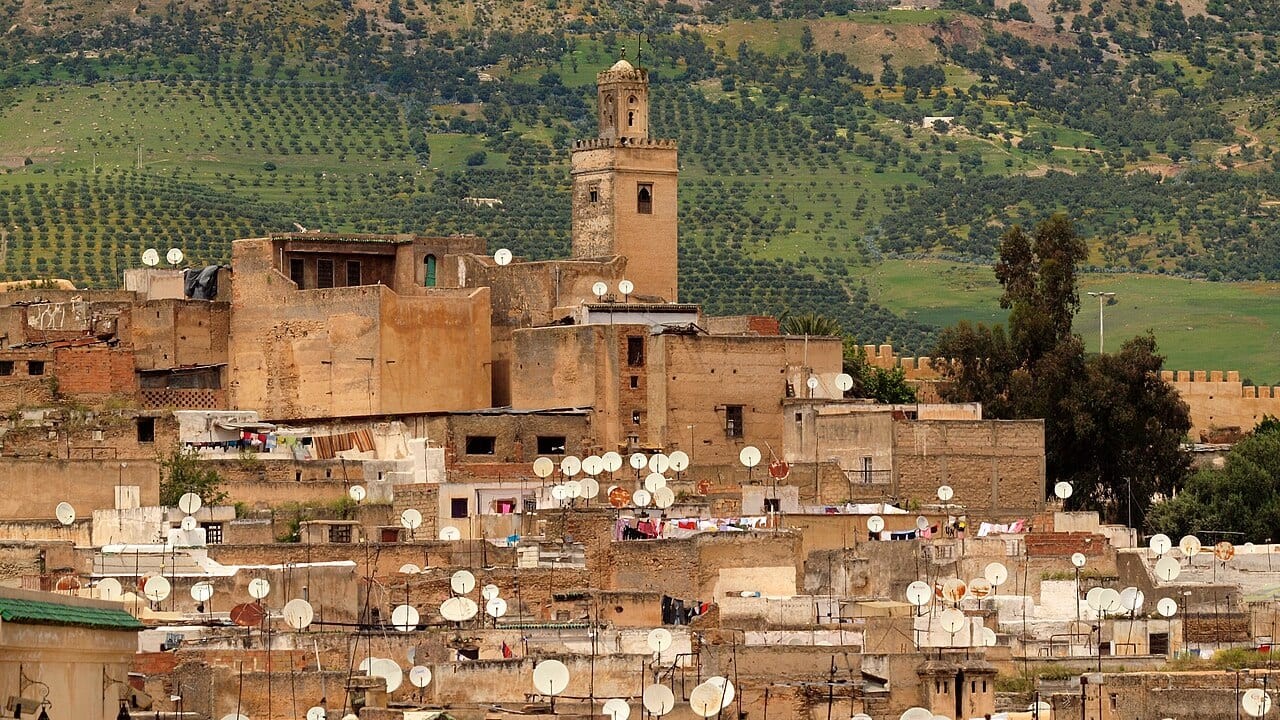
Fez City Guide
Morocco
Fez is Morocco's spiritual and cultural capital in the Fès-Meknès region, home to Fès el-Bali, the world's largest car-free urban area and a UNESCO World Heritage medina founded in the 9th century. Morocco is one of the more open North African markets for foreigners, who may freely buy urban and residential property; the only major restriction is on agricultural land, which non-citizens generally cannot own outright. Fez is a slower, value-oriented market than Marrakech or Casablanca, with transaction volumes rising in 2025 and property near announced infrastructure projects gaining a modest 5-10% during planning and a further 10-15% on completion. Investors split between heritage riads in the medina, which suit boutique guesthouse conversions but carry high renovation and access costs, and modern apartments in Ville Nouvelle and the Narjiss district, where rental demand is steadier. Gross residential yields are moderate at roughly 5-7%.
Marrakech
Morocco
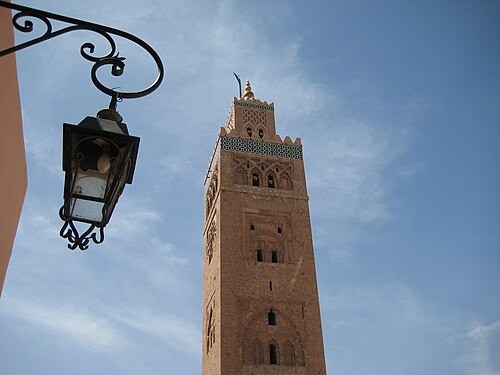
Marrakech is Morocco's most internationally recognised city -- the 'Red City' of UNESCO-listed medina, ochre walls, Atlas Mountain backdrop, and a tourism economy that has drawn European retirees, second-home buyers, and creative-class purchasers for decades. The city is consistently one of North Africa's strongest property markets for foreign buyers. Residential prices vary widely by sub-market: traditional riads in the medina sell for MAD 8,000-15,000 per square metre, while villas in the Palmeraie or Hivernage districts run MAD 15,000-30,000 per square metre (USD 1,500-3,000). Modern apartments in Gueliz are MAD 10,000-18,000 per sqm. Gross yields on short-let riads can reach 8-12% with good management; long-let yields are more modest at 4-6%. For international buyers, Marrakech offers Mediterranean lifestyle, strong tourism-driven short-let yields, freehold for foreigners with no restrictions, USD/EUR-stable MAD (managed peg basket), and a well-established expatriate community. The catch: liquidity is patchy outside core districts, the riad renovation market has hidden complexity, and resale times can run 6-18 months.
Rabat City Guide
Morocco
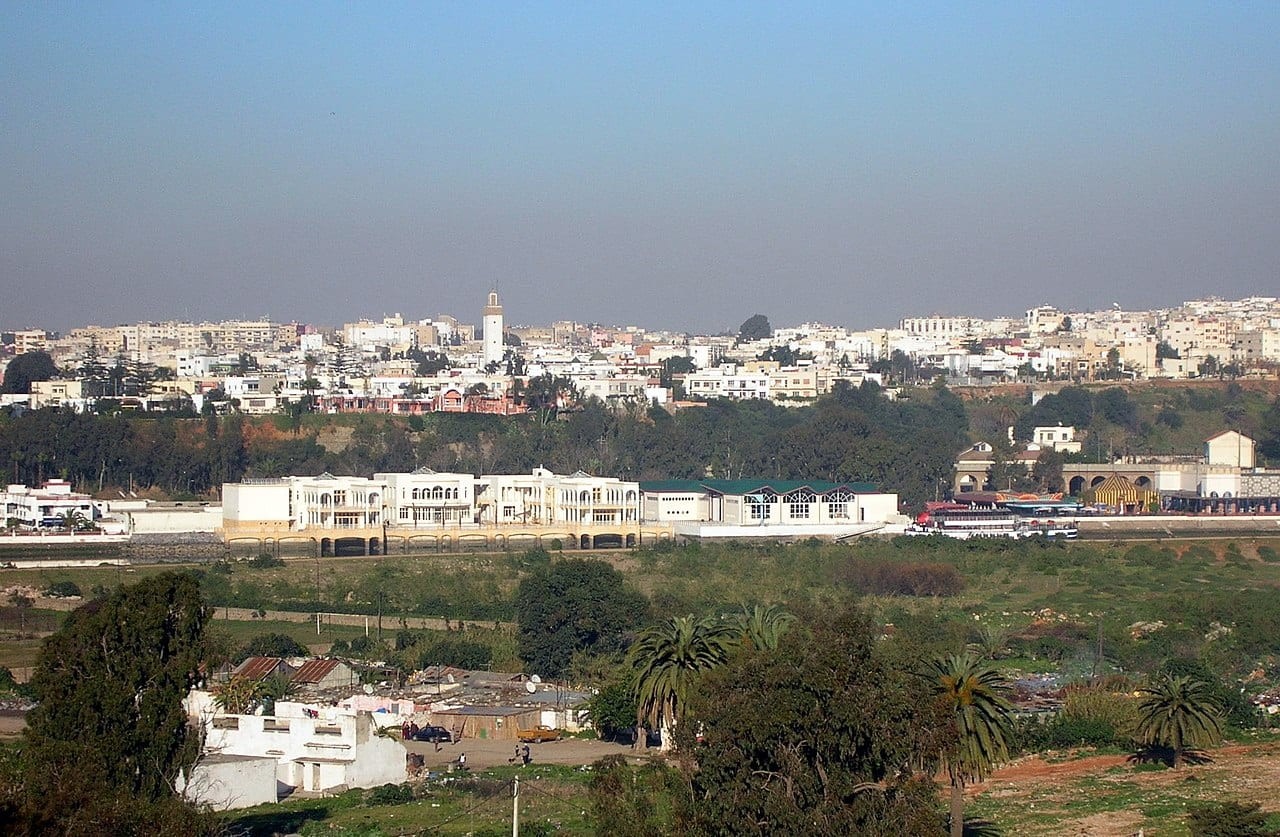
Morocco's political capital and a UNESCO World Heritage city, Rabat combines administrative stability with the country's strongest recent property momentum. As the seat of government and diplomacy, the city draws steady demand from civil servants, embassies, professionals, and a large returning diaspora - a tenant base less cyclical than tourism-led Marrakech or commercial Casablanca. Investment activity concentrates on the leafy prime districts of Agdal and Hay Riad, the premium villa enclaves of Souissi and L’Orangeraie, fast-appreciating El Menzeh, and the gentrifying Bouregreg waterfront and Bab Al Bahr zone across the river in Salé. Average prices sit around MAD 14,000 per square metre, rising beyond MAD 20,000 in prime Souissi, while three-bedroom apartments in Agdal trade at MAD 2-3.5 million. In late 2025 Rabat posted the strongest quarterly performance of Morocco's major cities - prices up 3.2% and transactions up 27% in a single quarter, outpacing Casablanca and Marrakech. With the Rabat-Salé tramway extension and improved highway links opening up previously overlooked areas, the city pairs 5-7% gross rental yields with steady appreciation for total-return-focused investors.
Tangier City Guide
Morocco
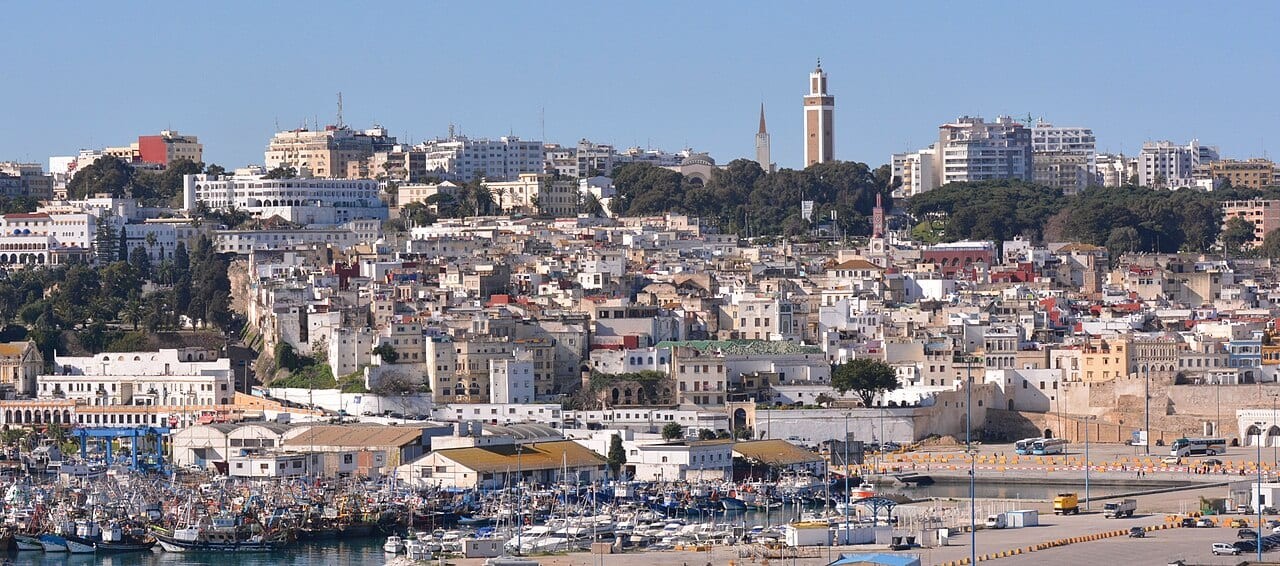
Guarding the Strait of Gibraltar at the meeting point of the Mediterranean and the Atlantic, Tangier has transformed from a faded international city into one of North Africa's most dynamic industrial and logistics hubs. The catalyst is Tanger-Med, Africa's largest port, whose expansion has drawn manufacturing, free-zone activity, and a wave of employment that is reshaping property demand across the metropolitan area. Investment focus centres on the seafront prime districts of Malabata and Iberia, the historic Medina, the city centre, and the new-build corridors radiating toward the port and free zones. Apartments average MAD 10,800-14,200 per square metre as of late 2025, with prime Malabata and Iberia commanding MAD 13,500-14,200 and luxury villas reaching MAD 16,300-18,500. Prices remain roughly 15% below comparable Casablanca stock, leaving room for the gap to narrow. The residential market has grown 4-6% annually - with prime seafront areas up 15-20% on infrastructure and the upcoming Africa Cup of Nations - while citywide gross rental yields average around 6.8%, rising toward 8-9% for well-run short-term holiday lets.

Amsterdam
Netherlands
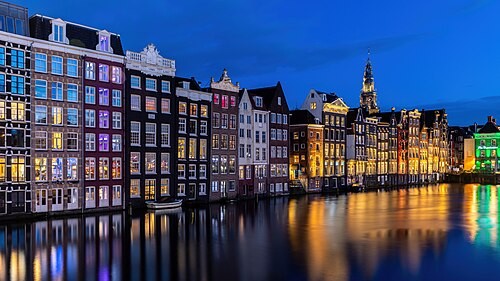
Amsterdam is the Netherlands' undisputed economic, cultural, and financial centre, and one of Europe's most expensive property markets per square metre. The city's UNESCO-listed canal belt, world-class tech sector, and post-Brexit financial services expansion combine with a chronic housing shortage to make Amsterdam one of Europe's most demand-saturated markets. Average residential prices run EUR 7,500-13,500 per square metre in central districts (Centrum, De Pijp, Jordaan, Oud-Zuid), with rental yields of 3.5-4.8% gross. The 2024 Wet Betaalbare Huur (Affordable Rents Act) extended mid-market rent caps to roughly 75% of the rental stock -- a major hit to buy-to-let yields -- while the 2026 transfer tax for non-owner-occupiers stands at 10.4%. Investors should model both carefully. For international buyers, Amsterdam offers world-class English-friendly professional services, an Anglosphere-style legal system on property, and the EU's most diversified tenant base (tech, finance, life sciences, creative industries). The catch: yields are tight, transaction taxes are punitive for non-owner-occupiers, and the regulatory environment has tilted decisively toward affordability.
Rotterdam
Netherlands
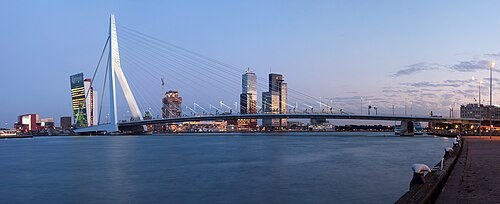
Rotterdam is Europe's largest port and the Netherlands' second city -- a working, gritty, architecturally bold counterpoint to Amsterdam's heritage charm. After WWII levelled the city centre, Rotterdam rebuilt as a showcase of modernist and contemporary architecture (Erasmus Bridge, Markthal, De Rotterdam, Cube Houses), giving it a distinct identity and tourist appeal. The property market offers 25-35% better value than Amsterdam on a price-per-square-metre basis: EUR 4,500-7,500 in central districts, with rental yields of 4.5-6.0% gross -- materially better than Amsterdam. Rotterdam has been the favoured Dutch alternative for value-focused international buyers since 2018, and prices have grown ~70% over the past decade. For international buyers, Rotterdam offers a working-port logistics economy (less cyclical than Amsterdam's tech/finance mix), strong tenant demand from Erasmus University students and port-related professionals, and English-friendly services. The same 2024 rent caps and 10.4% transfer tax apply as elsewhere in NL. Best suited for income-focused investors comfortable trading prestige for yield.
The Hague City Guide
Netherlands
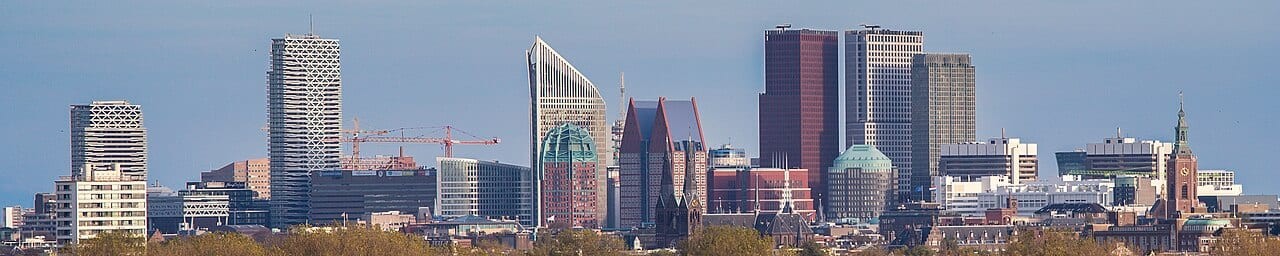
The Netherlands' seat of government and the international city of peace and justice, home to the International Court of Justice, Europol and more than 200 international organisations, The Hague offers investors a uniquely stable, expat-driven rental market on the North Sea coast. A vast civil-service workforce and a dense diplomatic community generate exceptionally durable demand, particularly in the elegant Statenkwartier and Archipelbuurt districts, where embassies and a walkable cosmopolitan character keep vacancy below 2% and 90–180 sqm apartments and townhouses range from €600,000 to €1,200,000. Among Dutch cities, The Hague stands out for income: its one-bedroom segment posts gross yields around 7.4% and monitored submarkets register the highest potential performance in the country at roughly 7.1%, well above Amsterdam, reflecting strong, government- and expat-anchored tenant demand against more moderate price levels. Major regeneration in the Central Innovation District (CID) and the former-industrial Binckhorst is expanding the supply pipeline and lifting demand. With Dutch national prices forecast to rise a moderate 4–5.5% in 2026 after the steeper gains of 2025, The Hague combines best-in-class Dutch rental yields, defensive tenant quality and steady appreciation, making it the country's standout choice for income-focused buyers.
Utrecht City Guide
Netherlands
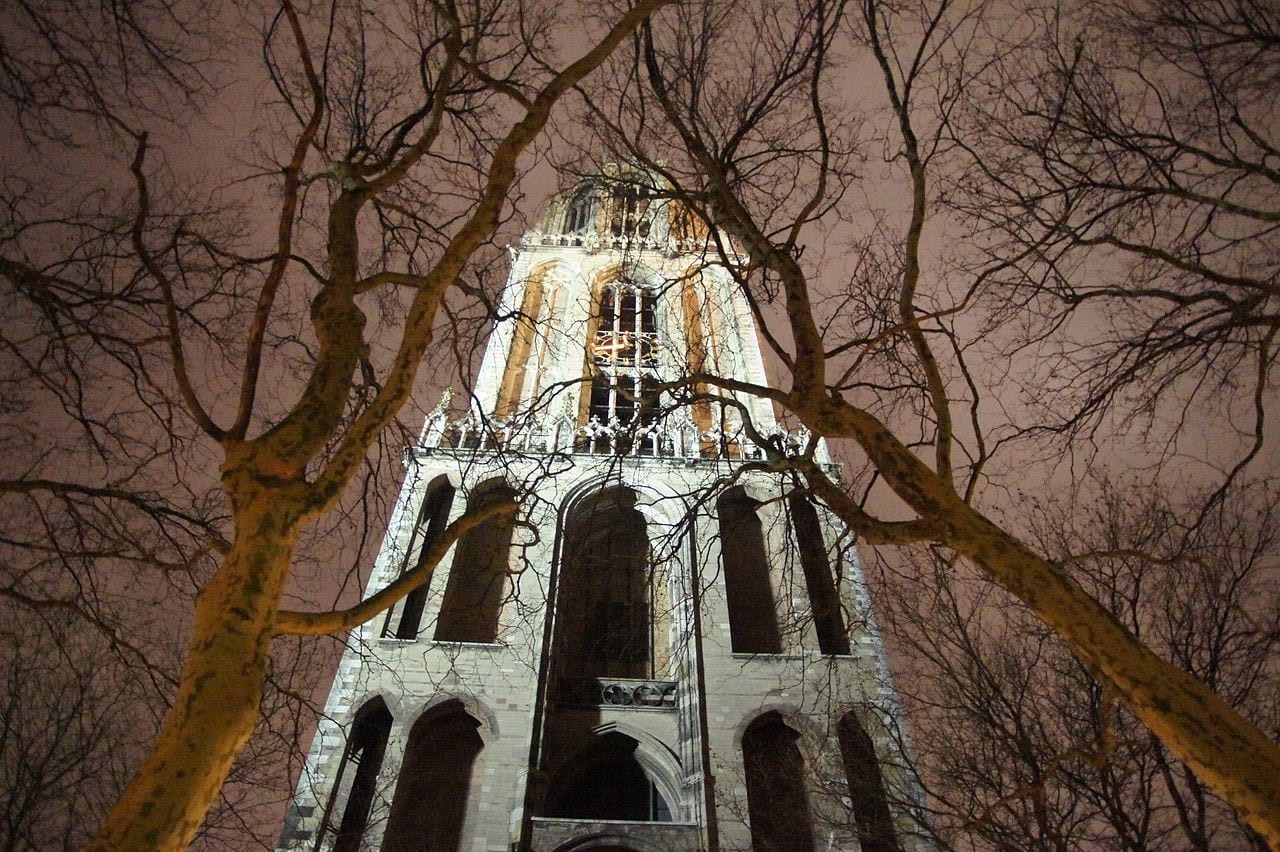
Sitting at the dead centre of the Netherlands and the country's main rail crossroads, Utrecht is the fastest-growing of the major Dutch cities and one of the most supply-constrained, a combination that has made it a standout for both rental yield and long-term capital appreciation. The medieval Binnenstad (old town), with its canal-level wharves, commands the highest prices at around €6,500 per square metre, while gentrifying districts like Lombok and family-friendly Wittevrouwen and Oog in Al offer relative value; the gap between the cheapest neighbourhood (Overvecht, near €4,000/sqm) and the priciest is roughly 60%. The median home price sits around €575,000, and properties typically sell about 8% above asking in a market where renter demand is outpacing new supply. Yields are strong by Dutch standards, studio and one-bedroom segments reach roughly 7.4% gross (with net yields of 4.8–6.3%), supported by a large student and young-professional population anchored by Utrecht University, the Netherlands' largest. The Merwede district buildout and the new Merwedelijn tram line are major catalysts adding thousands of homes and lifting connectivity. With national prices forecast to climb 4–5.5% in 2026 and the Utrecht region expected to outpace Amsterdam, the city offers investors a rare blend of high yield and durable growth.

Granada
Nicaragua
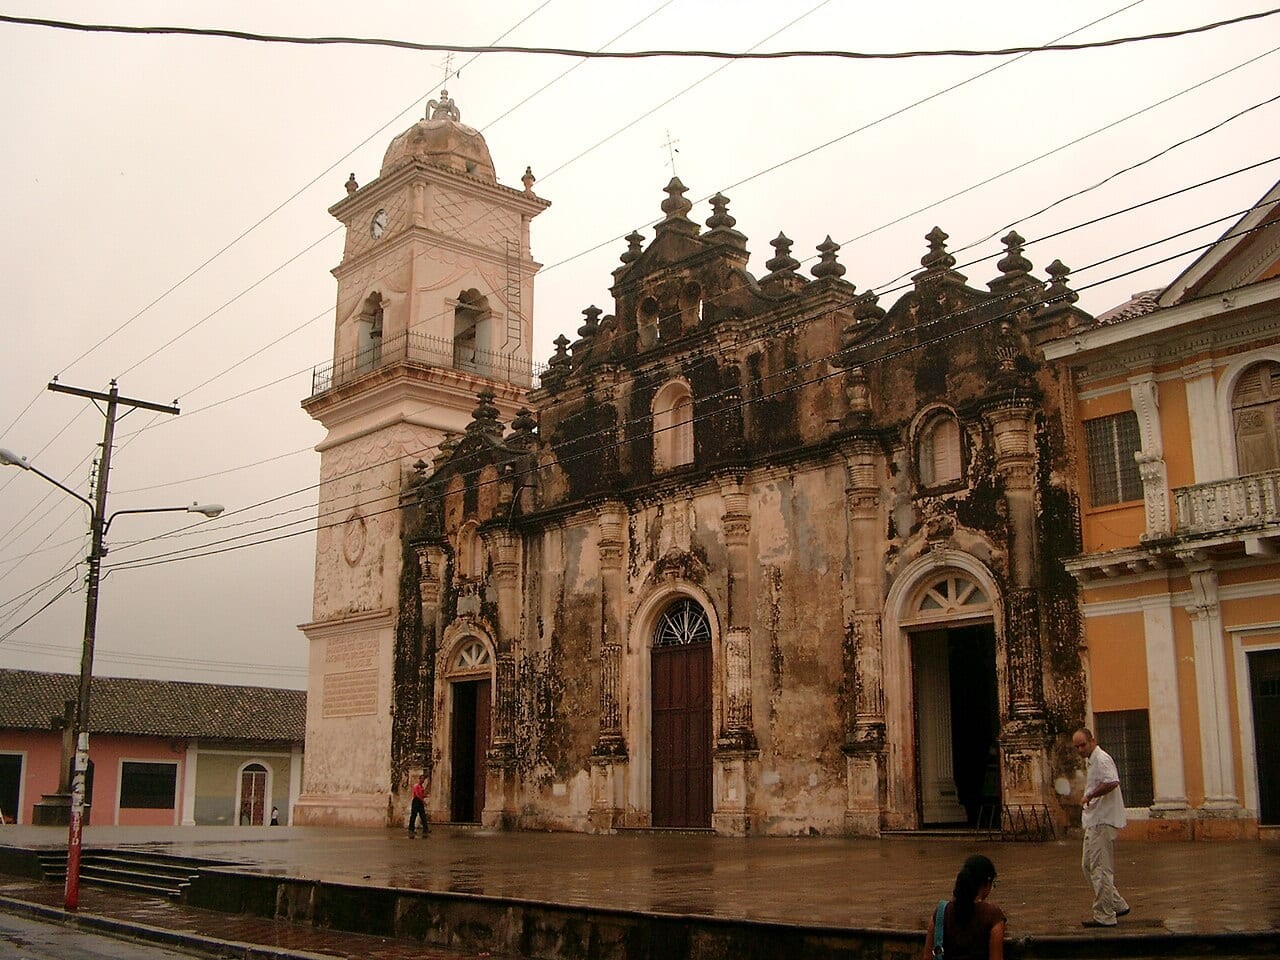
Granada is Nicaragua's marquee heritage market and the country's most established foreign-buyer destination. Founded in 1524 on the shores of Lake Cocibolca, its grid of cobblestone streets and pastel colonial facades draws retirees, lifestyle migrants and boutique-hotel operators. In 2026 restored colonial homes trade at roughly USD 878 per square metre on average, with premium Centro Historico properties commanding USD 1,150 to 2,200 per square metre; entry-level character homes still start near USD 60,000 while turnkey restored houses run USD 80,000 to 200,000 and trophy courtyard mansions reach USD 500,000. Short-term rental occupancy of restored homes sits around 60 to 70 percent at average daily rates of EUR 80 to 100, but net yields settle near 4 to 5 percent once management, maintenance of old structures and seasonality are counted, making Granada primarily a capital-appreciation and lifestyle play. The colonial core is forecast to grow 7 to 10 percent in 2026 and 35 to 50 percent cumulatively over five years on limited restored-home supply. Foreigners enjoy full ownership rights identical to nationals, no residency is required to buy, and property purchases of USD 50,000 or more qualify for Nicaragua's investor-residency program. Note the January 2025 currency law requiring domestic pricing in cordobas, though foreign-currency housing payments remain exempt.